
Cash Stuffing: How It Works and Who It Suits
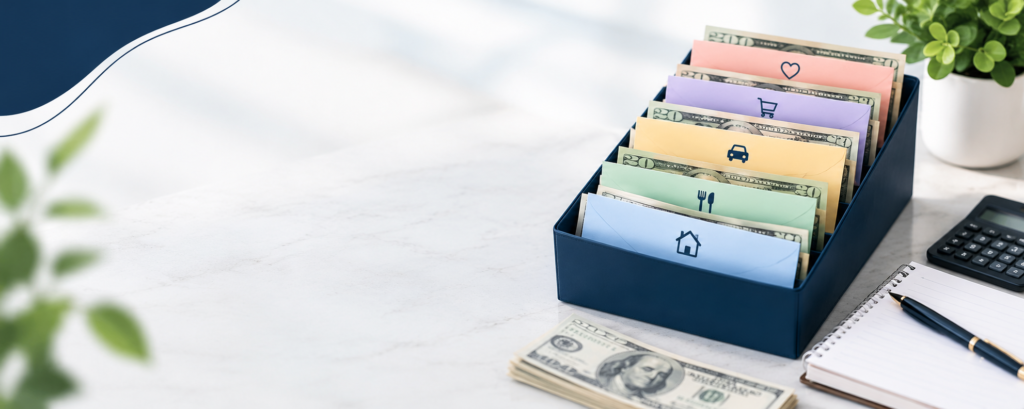
Picture the 19th of the month. The grocery money is gone, you can’t even remember buying anything big, and there are eleven days left. That’s the mess cash stuffing was made for.
What is cash stuffing, and why is everyone doing it?
What is cash stuffing? Short version: you pull some of your paycheck out in cash, sort it into labeled envelopes (groceries, gas, fun money), and that’s all you get to spend in each category until the next payday. Envelope’s empty? You’re done.
It’s the envelope method your grandparents used, just with better branding. Scroll social media and you’ll find glossy binders, stickers, and oddly relaxing videos of bills being counted into piles. Cute, sure. The stickers aren’t doing the work, though.
What does the work do? The sting. Tapping a card costs you nothing, mentally. Peeling three twenties out of a grocery envelope that already looks thin is different. You feel that. Apps haven’t managed to copy it, and I doubt they ever will.
How cash stuffing works, step by step
Pay the fixed stuff (rent, loans, utilities) straight from your bank account. Those never go in an envelope.
Take your pay and subtract bills and savings. Whatever’s left is what you can stuff.
Decide how it splits across categories, then withdraw the total.
Put the cash into cash stuffing envelopes, or into pouches in a cash stuffing binder.
Spend from the matching envelope only. Empty means done.
Here’s a made-up example so the numbers feel real. Say $2,400 comes in after tax and $1,700 is already spoken for. That leaves $700: $300 groceries, $100 gas, $120 eating out, $80 fun, $60 personal care, and $40 you don’t assign yet.
One small thing nobody mentions: ask for small bills when you withdraw. A single $100 note is awkward to split across four cash stuffing envelopes, and breaking it at the store defeats the purpose. Twenties, tens, and a few fives make cash stuffing a lot less fiddly.
Paid weekly? Or do you know you go a bit wild in week one? Stuff weekly instead. Nobody says it has to be monthly.
And you don’t have to go all-cash. Plenty of people keep the card for bills and online orders and use cash only for the two or three categories that always leak.
Cash stuffing binder or envelopes: which one first?
Start with cash stuffing envelopes. I’ll defend that.
They cost almost nothing, and if you hate the habit by week two, you’ve lost a couple of dollars, not a big chunk of your budget. Plain paper tears quickly, so go for laminated or plastic if you can.
A cash stuffing binder is the same thing as a zipper and a handle. Most cash stuffing binder styles are small, with clear pouches for each category and a spot on the front for the amount. Tidier, easier to carry, nicer to look at. But the pattern is common: someone buys the full setup, feels organized for ten days, then drifts off because the habit never took. Buy the cash stuffing binder after the habit sticks. As a reward.
Labels matter more than you’d think. Write the category and the starting amount on every one of your cash stuffing envelopes, and jot down what you spend, even loosely. A running total on the front tells you more than an empty envelope does, because you see the trend before you hit zero.
Envelope Binder
Cost: Very low or higher
Holds up tears, gets lost, lasts longer
Carrying just one bulky thing in a small bag
Good for trying the method Lots of categories
Do cash stuffing wallets beat a binder?
Sometimes, yes. A cash stuffing wallet is a slim zip wallet with dividers or card slots. If you only run three or four categories and you’re carrying them every day, it makes more sense than a binder sitting in a drawer.
The annoying part of any home setup is standing in the checkout line while the grocery envelope sits in a drawer at home. Cash stuffing wallets fix that. The catch is space. In the past five categories, the wallet turns into a brick. Plenty of cash-stuffing wallets also have a clear window or a card slot, which is handy for a little receipt. So I’d treat a cash stuffing wallet as the carry version, with the bulk of the money in the binder at home and one week’s worth in the wallet.
Which cash stuffing categories get an envelope?
Anything where the amount changes and you’re the one spending it. Groceries, gas or bus fare, eating out and coffee, fun money, personal care, and maybe pets or kids’ extras. Some people add sinking funds too (car repairs, gifts, yearly fees), and those envelopes just fatten up slowly.
Rent, insurance, and subscriptions stay out. Paying them in cash is a pain and does zero for self-control.
Start with four or five cash stuffing categories, not fifteen. You can always split “fun” into two later, once you know where the money actually goes. Anyone who opens twelve envelopes on day one is usually done by week three.
Cash stuffing vs. digital budgeting: pros and cons
Here’s my honest read on cash stuffing vs. digital budgeting: pros and cons.
Cash makes spending visible, and the stinging part slows you down. No app, no bank link, no monthly fee. But nobody totals anything for you, online shopping barely fits, and a lost wallet means lost money.
Apps are better at detail: automatic sorting, trends, recurring payments, and online orders. Where they lose is felt. Spending stays abstract, and some charge a monthly fee.
You’ll hear that cash is always better for overspenders. I don’t buy it. If most of your money leaves online, no envelope can reach it. What works better for most people is both: an app for the big picture, cash stuffing envelopes for the categories you can’t trust yourself with.
Is cash stuffing for you?
Cash stuffing fits if groceries, takeout, and small “I deserve this” purchases keep eating your paycheck, or if you’ve installed three budgeting apps and ignored all of them.
It fits badly if your pay and bills all run on direct deposit and autopay and you mostly shop online. Cash stuffing envelopes can’t touch a streaming subscription. A separate sub-account at your bank does a similar job without the paper, and the same goes if you can’t keep cash safely at home.
So what is cash stuffing good for? A narrow thing. Variable spending you can touch. For plenty of people that’s the part that hurts.
Where the habit falls apart
Borrowing between envelopes, mostly. Fine once in a while, but write it down or the whole system melts back into one pile.
Then there’s stuffing too little. Putting $200 in groceries when you really spend $400 isn’t discipline; it’s a setup. Check three months of statements before choosing cash stuffing categories and amounts.
What to do with leftovers? Decide before the month ends. Money left in a cash stuffing envelope can roll over or go to savings, but pick one.
If you carry debt or your income swings a lot, a licensed financial advisor or nonprofit credit counselor can look at your actual numbers before you commit to anything.
Questions people ask about cash stuffing
What is cash stuffing in simple terms?
It’s a budgeting method where you withdraw cash for spending categories like groceries or gas, put each amount in its own envelope or binder pouch, and spend only from that envelope. When the cash is gone, you stop spending in that category until your next payday.
Is cash stuffing worth it?
It’s worth it if overspending on variable costs like food and fun is your main leak. Physical cash makes spending visible, which slows most people down. It’s less useful if most of your spending is online or automated, where a digital budget fits better.
How much money goes into each of your cash stuffing envelopes?
Check three months of bank statements, find your average spend per category, and use that as your starting number. Round to the nearest five dollars so counting stays easy. Adjust after a month. Fixed bills like rent stay in your bank account, and only flexible spending gets cash.
Are cash stuffing wallets and binders safe?
Mostly, if you keep the amount small. Carry only what you need for the week, store the rest somewhere secure or leave it in the bank until stuffing day, and keep your name and address off any binder. Lost cash is gone for good.
This week, do one thing. Pull last month’s statement, find what you spent on groceries, and take out one week’s worth in cash. Plain envelope, amount written on the front. No cash stuffing binder yet. Then see what happens on day five when it’s nearly empty.